Published November 10, 2026
Fix It, Credit It, or Cut the Price? Negotiating After the Inspection in Livingston County
There's a common belief that once the inspection report comes back, the buyer's job is simple: send the seller the list and ask them to fix everything.
That rarely works, and it can sour a deal that should have closed. Around Brighton, Howell, Hartland, Pinckney and Fowlerville, a lot of the homes I walk through are older ranches, farmhouses on acreage, or lake properties that have been updated in stages. Almost every inspection turns up something. The real question isn't whether there's a list. It's how you handle what's on it.
You usually have three ways to go: the seller makes the repair, the seller gives a credit, or the price comes down. Each one works differently, and in a Michigan winter the timing matters more than people expect.
I grew up around construction with my family, so I tend to look at a repair request the way a contractor would: what's the actual fix, who should do it, and can it realistically get done before closing? I'm not a builder or an inspector, but I can help you ask those questions before you put anything in writing.
Start by Sorting the Report
A 40-page report can make a solid house look like a disaster. Before you ask for anything, separate it into three piles:
- Safety and big-ticket items: things like active roof leaks, electrical hazards, a failing furnace, structural concerns, or well and septic problems.
- Real but manageable: an aging water heater, a gutter that needs re-hanging, a GFCI outlet that doesn't trip.
- Normal wear: caulking, a sticky door, a worn deck board.
Lead with the first pile. Sellers are a lot more willing to work with you on a short, reasonable list than on 60 line items.
Pro Tip: If the inspector flags something for "further evaluation by a qualified professional," get that professional out during your inspection window. A real quote or diagnosis is far stronger in a negotiation than a guess.
Option 1: The Seller Makes the Repair
This feels like the cleanest answer, and sometimes it is. But you don't control who does the work, what materials get used, or how carefully it's done. The seller is motivated to get it done, not necessarily to do it the way you would.
If you go this route, put the details in writing: what's being repaired, that it'll be done by a licensed contractor where the work requires one, and that you'll get receipts and any permit paperwork before closing. Plan on a walk-through or re-inspection to confirm it's finished.
Winter adds a wrinkle. Roofing, grading, concrete, exterior paint and some septic work can be hard to schedule, or done poorly, once the ground freezes and the snow shows up. If the repair is weather-dependent, have an honest conversation about whether it can really happen before your closing date.
Pro Tip: Ask the seller's contractor to describe exactly what they're fixing. "Repaired roof" on an invoice tells you a lot less than "replaced flashing and decking around the chimney."
Option 2: A Seller Credit at Closing
With a credit, the seller agrees to pay part of your closing costs instead of doing the work. You then handle the repair after you own the house, with your own contractor and your own standards.
For a lot of buyers, especially anyone comfortable with a little sweat equity, this is the best of the three. You choose the fix. You don't have to rely on the seller's rushed repair job.
There are limits, though. Your loan program may cap how much the seller can contribute, and a credit usually applies to closing costs and prepaids rather than coming back to you as cash for repairs. If the credit exceeds what you can actually use, part of it may be wasted. Check with your lender on the numbers before you agree to anything.
Pro Tip: Base your credit request on actual contractor quotes when you can. A number backed by a written estimate is much harder to argue with.
Option 3: Lower the Purchase Price
A price reduction lowers what you're paying for the house, and with it, your loan amount and possibly your property taxes down the road. It doesn't put money in your hand at closing, though, so you'll need the cash for the repair yourself.
This option can make sense for a bigger item you're not planning to tackle right away, or when a credit would exceed what your lender allows. It can also help if the appraisal is already tight.
Pro Tip: Run the numbers both ways with your lender. A small price reduction often changes your monthly payment only slightly, while a credit can lower the cash you need to bring to closing.
What Sellers Should Know
If you're listing this winter, a pre-listing inspection or a focused look at the roof, furnace and well and septic can take some surprises off the table. Fixing obvious items before you list, or at least getting quotes, gives you more control than reacting to a buyer's list under a deadline.
When a request does come in, don't take it personally. A reasonable credit is often simpler for everyone than scrambling to find a contractor in December.
Keep Reading
- Buying in the Snow? What a Winter Home Inspection Can, and Can't, Tell You
- Will They Insure This House? What Home Insurance Can Do to a Livingston County Deal
- The True Value of Sweat Equity
The Bottom Line
Sort the report, focus on what matters, and pick the option that fits the repair, your loan and the calendar. Fix, credit or price cut, the goal is the same: get to closing on a house you're comfortable owning.
If you're buying or selling around Brighton, Howell, Hartland, Pinckney, Fowlerville or Lansing and want help reading an inspection report or putting together a reasonable request, call or text me at 810-522-0558.
Devin Fink | DJF Properties | Rademacher Team and Associates | KW Professionals
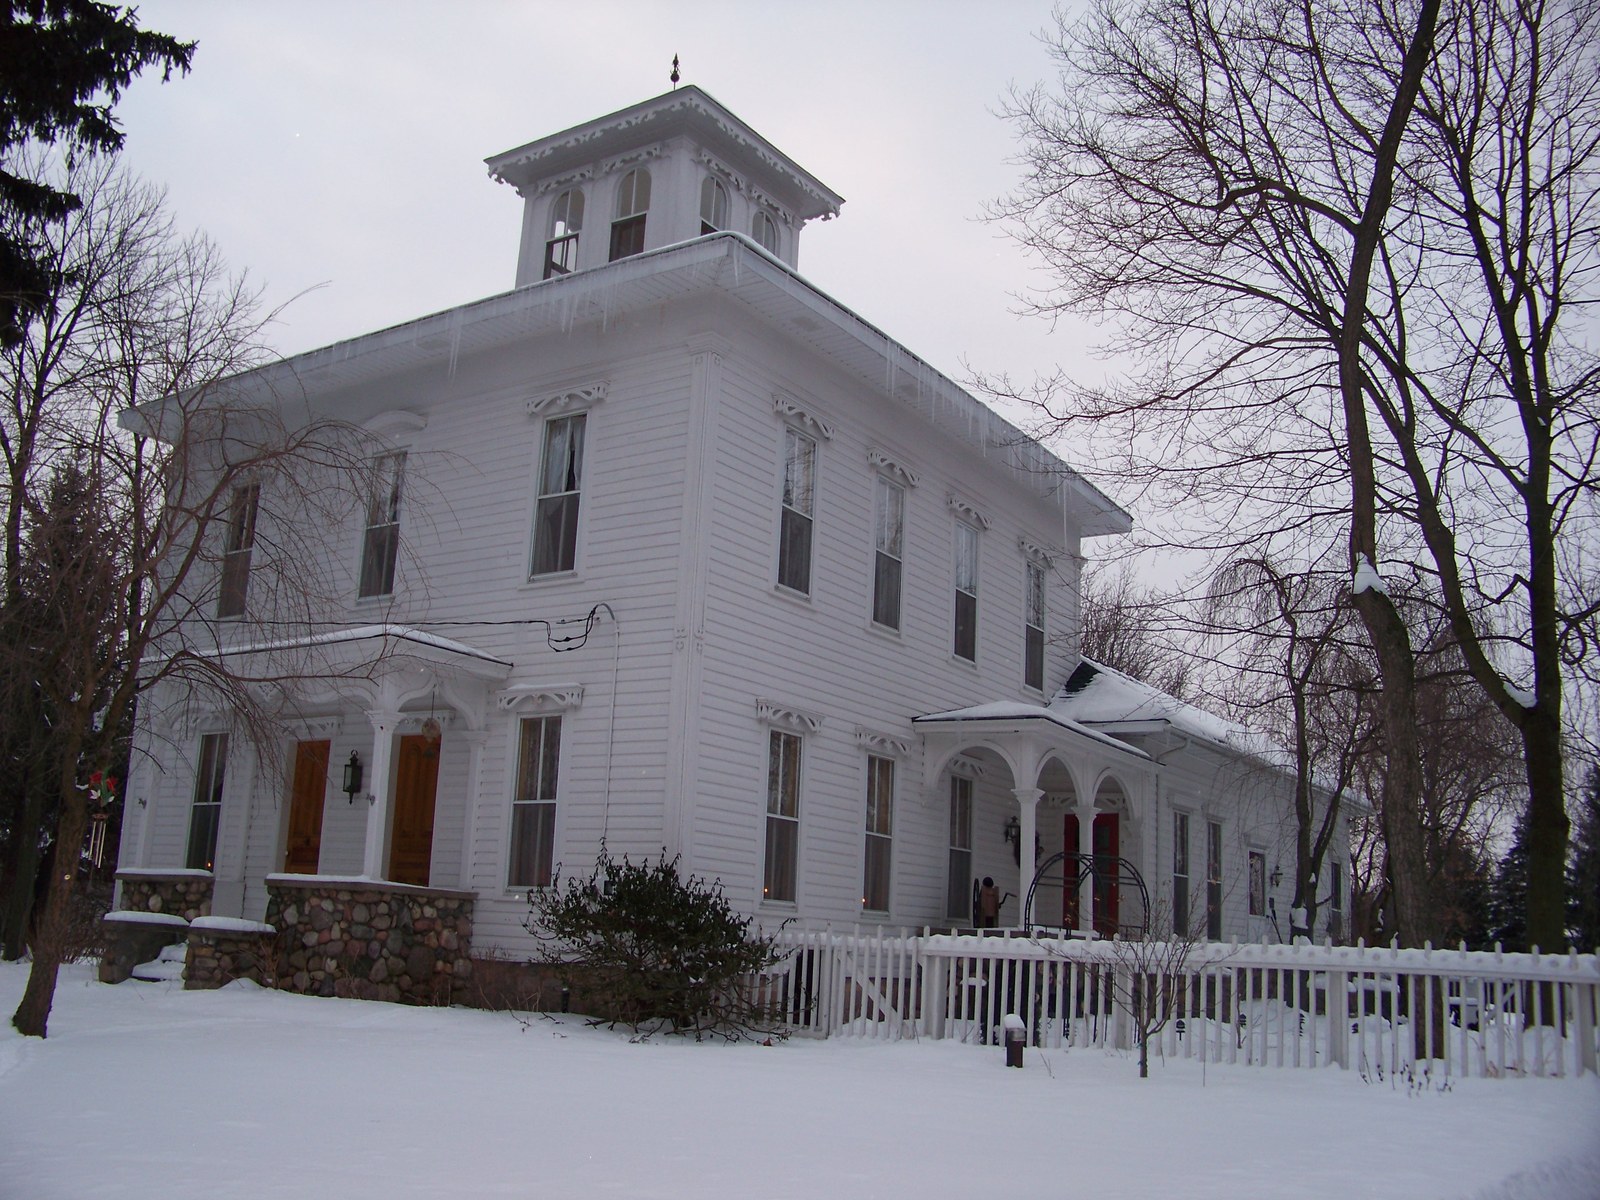
Photo: Annebethmi, August Westphal Farmstead, Brighton, Michigan, via Wikimedia Commons, CC BY-SA 3.0. Resized.
