Published November 8, 2026
Will They Insure This House? What Home Insurance Can Do to a Livingston County Deal
Home insurance can feel like one more box to check before closing. Find a house, get through inspections, call for a policy, and move on.
Around Brighton, Howell, Hartland, Pinckney and Fowlerville, it deserves a spot on the list much earlier. A quote might come back higher than you budgeted. A carrier might have questions about the roof or wood stove. Or you might discover that a township property gets rated differently than the subdivision you’re moving out of.
If you’re financing the purchase, your lender will need acceptable proof of insurance before closing. Waiting until the last few days leaves very little room to solve a problem.
I grew up around construction with my family, so on tours I notice things worth asking about: the roof, the chimney, how the house is heated, and access to the property. I’m not an insurance agent, and I’m not here to quote a premium. I am here to help you ask the right questions early enough that insurance doesn’t stall the deal.
Shop the Policy When You Shop the House
Start as soon as you’re under contract—ideally during the inspection window, not the week of closing. Talk with a licensed insurance agent familiar with Livingston County and township properties.
Give them the address, year built, roof age if you know it, and whether there’s a wood stove, pellet stove, pool or trampoline. If you’re working with an independent agent, ask which carriers they can compare.
One company declining a property doesn’t necessarily mean every company will. But you want time to find that out before your closing appointment.
Pro Tip: Ask your lender early what insurance documents they need, when they need them, and the exact mortgagee information your insurance agent should use.
The Roof Is an Early Question
Age, material and condition can affect whether an insurer will offer coverage and what that coverage costs. A roof that looks fine from the street may still raise questions.
Ask whether roof damage would be covered at replacement cost or actual cash value, whether a separate wind or hail deductible applies, and whether the policy has any roof-specific limitations. A cheaper premium isn’t automatically the better deal if the coverage is different.
I don’t pretend I can date a roof from the driveway. I do watch for curled or missing shingles, attic staining, patches of different ages and tired chimney flashing. Those are reasons to ask more questions—not a diagnosis.
If the roof is questionable, get it into both the inspection and insurance conversations early. A seller credit can help with a future repair budget, but it doesn’t automatically make an insurer willing to cover the house in its current condition.
Pro Tip: Ask the seller for roof receipts, installation dates and warranty paperwork. Documentation is more useful than a verbal “I think it’s about eight years old.”
Township Lots and Fire Protection
Outside city subdivisions, you may not have a fire hydrant near the driveway. Insurers can consider fire protection, including distance to a station and access to a water supply, when evaluating a property.
That doesn’t mean a five-acre lot is uninsurable. It means you shouldn’t assume the quote will match a similar house in a subdivision with hydrants nearby.
The same goes for access. If there’s a long driveway, a narrow entrance or a steep section that gets difficult in winter, describe it accurately and let your insurance agent tell you whether it matters to the carrier.
Pro Tip: Don’t guess at the property’s fire-protection classification. Give the agent the address and ask them to verify it.
Wood Stoves, Chimneys and Other Questions
Wood stoves and inserts are common in older farmhouses and ranch homes around here. Depending on the carrier, you may be asked about installation, clearances, inspections or chimney maintenance.
I won’t certify a stove or chimney. I will flag one during a showing so you can involve your insurance agent and a qualified professional before you commit to a plan.
Pools, trampolines, older electrical systems, prior claims and a home that will sit vacant during renovation can also affect coverage options. None should be left out of the conversation because you’re hoping it won’t come up.
Pro Tip: If you plan to renovate before moving in, tell your insurance agent up front. Ask whether you need different coverage during vacancy or construction.
What Sellers Can Do Before the Sign Goes Up
If you’re listing in Brighton, Howell or the surrounding townships, gather the roof paperwork and relevant service records before a buyer asks. If there’s a wood stove, have any installation and inspection documentation available.
Be accurate about what you know, and don’t promise that a buyer will get the same policy or premium you have. Their insurer and circumstances may be different.
A November or December buyer may already be working around holiday schedules. I covered the loan side in Buying Over the Holidays. Insurance is another part of that timeline worth starting early.
If several carriers decline a property, ask a licensed agent about available alternatives. Michigan’s Basic Property Insurance Association, often called the FAIR Plan, provides a last-resort option for eligible properties. It isn’t a substitute for comparing coverage, and eligibility and lender acceptance still need to be checked.
Keep Reading
- Buying Over the Holidays? How to Keep Your Mortgage Approval on Track Through Closing
- Buying in the Snow? What a Winter Home Inspection Can—and Can’t—Tell You
- Understanding Michigan’s Pop-Up Property Tax
The Bottom Line
Start shopping for insurance early, compare coverage as well as premiums, and tell your agent about the roof, stove and any renovation plans. Don’t leave a question that could affect closing until the week you’re supposed to get the keys.
If you want a second set of eyes on a house around Brighton, Howell, Hartland, Pinckney, Fowlerville or Lansing, call or text me at 810-522-0558. Happy to walk it with you and help keep the timeline realistic.
Devin Fink | DJF Properties | Rademacher Team and Associates | KW Professionals
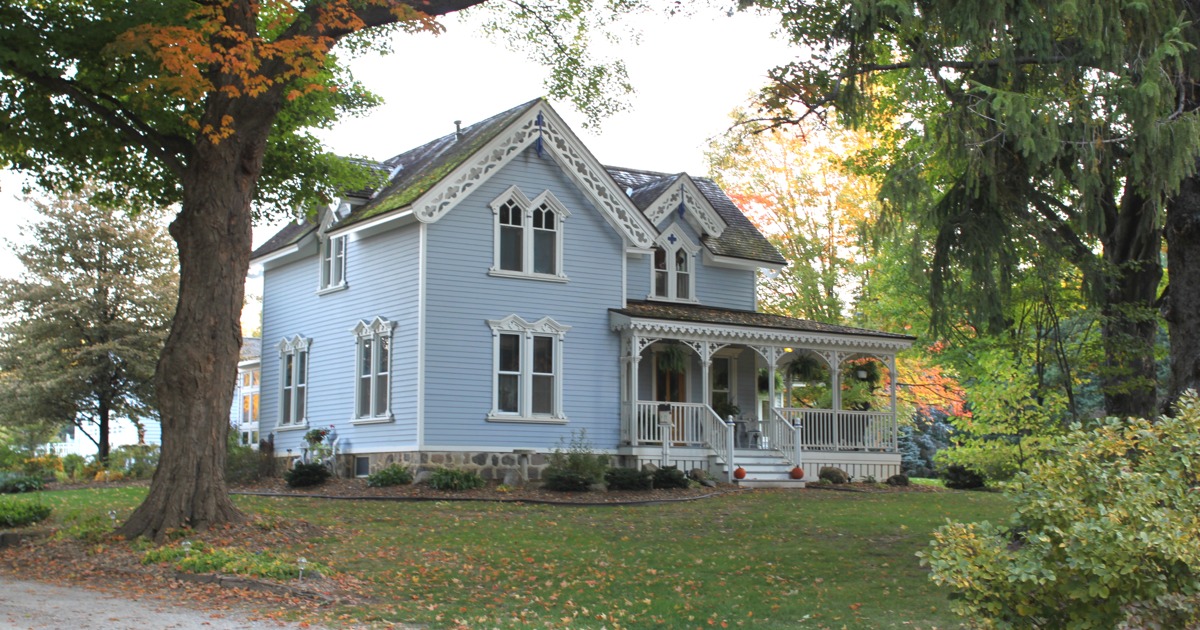
Photo: Dwight Burdette, Rural Residence, 8171 Brookeville Road, Salem Township, Michigan, via Wikimedia Commons, CC BY 3.0. Cropped and resized.
